“Indian companies that migrate quickly from high-volume generics to speciality pharmaceuticals will be successful in the coming decade”
June 01, 2026 | Monday | Views | By Dr Manbeena Chawla
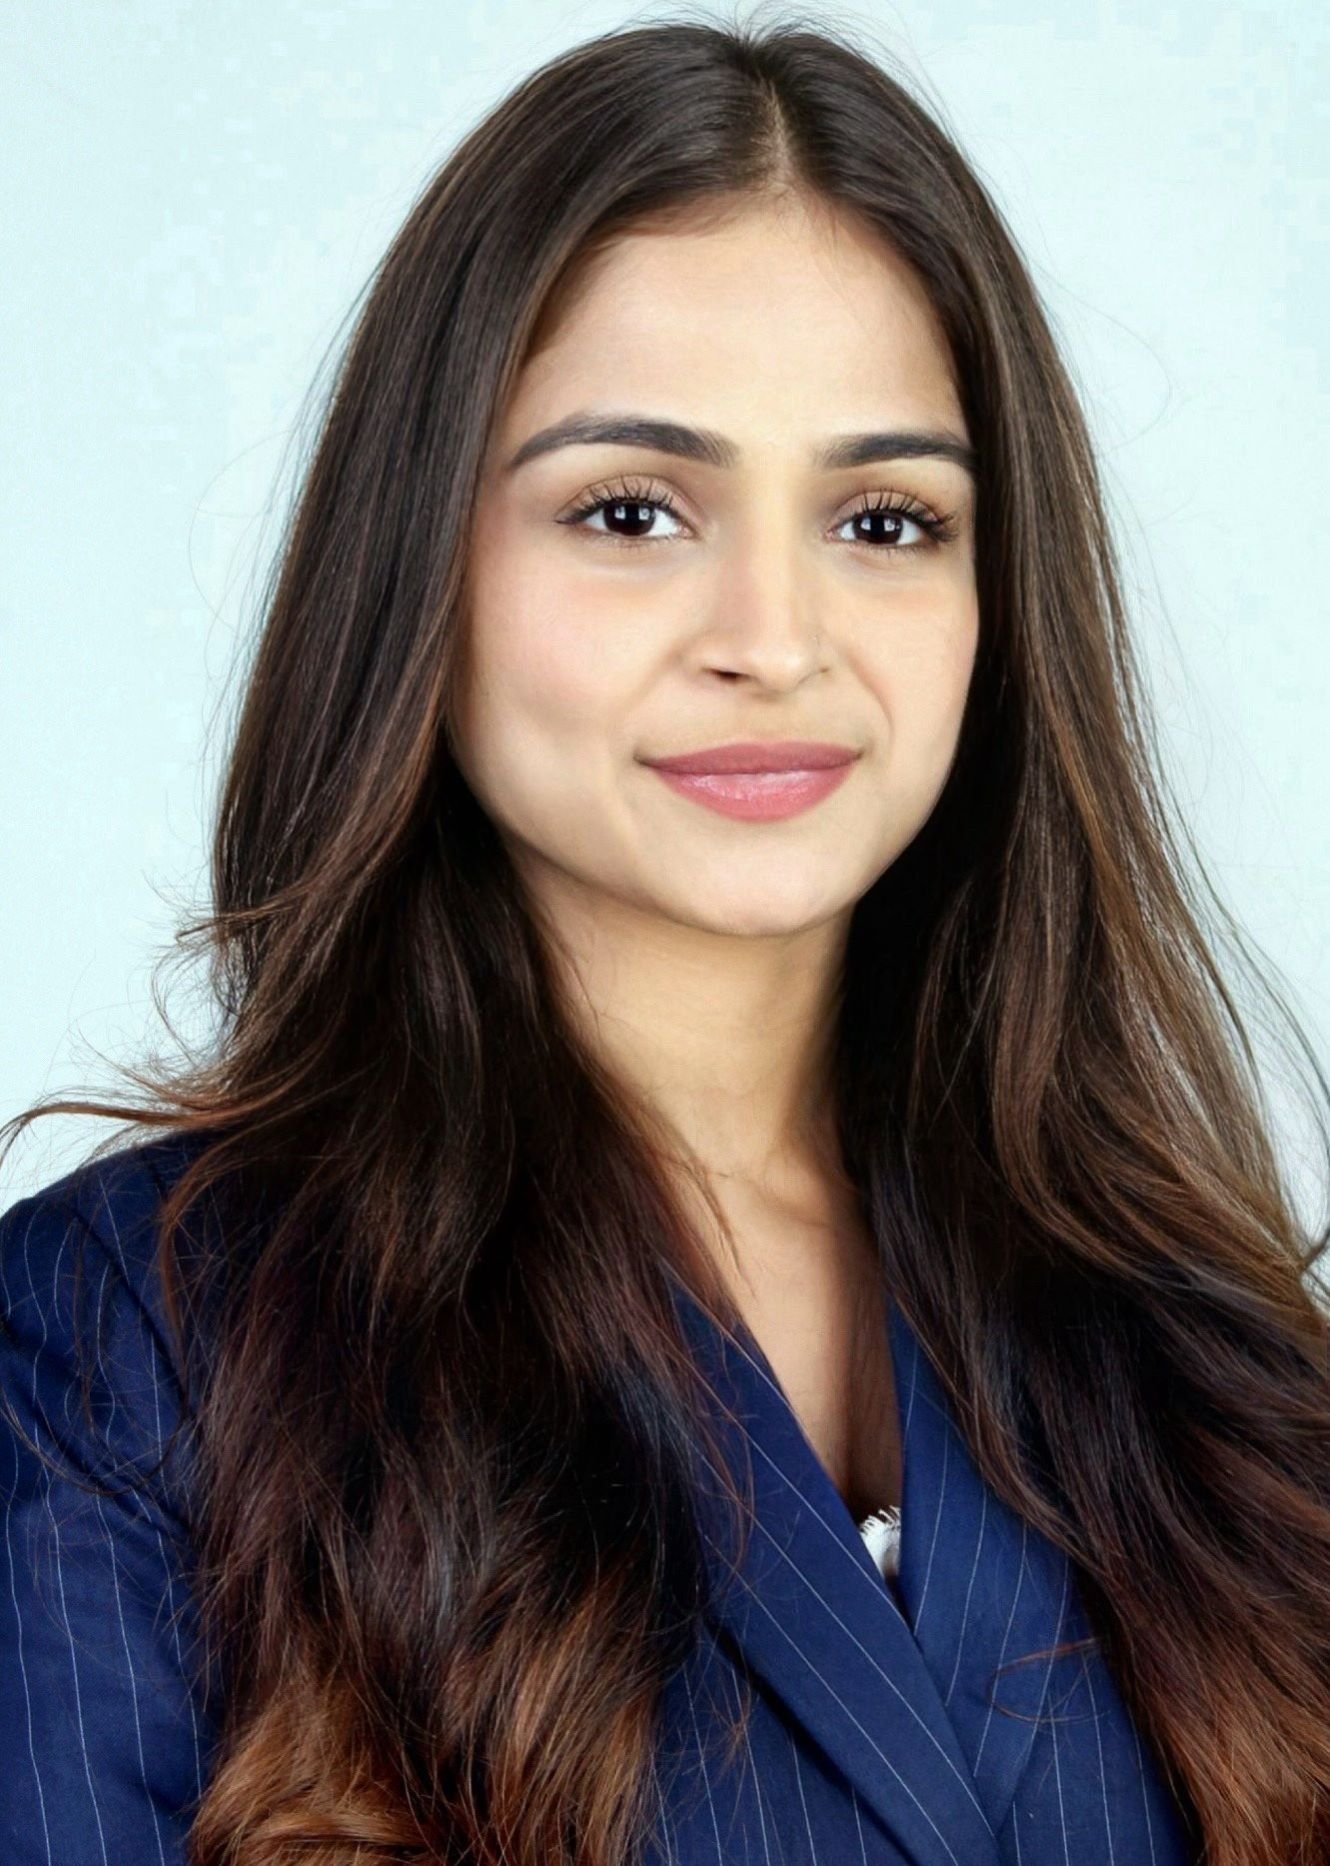
The estimated size of the Active Pharmaceutical Ingredient (API) market in India in 2025 was $14.77 billion, projected to reach $15.28 billion in 2026, marking a record high in market size and global influence. With the Indian API market poised for robust growth driven by increasing demand, supportive government policies, and technological advancements, the pharma players are inching towards the global spotlight. One such major player, Mumbai-based Supriya Lifescience, is completing 40 years in the pharma API sector. To find out more about the company’s growth plans and the opportunities that lie ahead for the Indian pharma industry, BioSpectrum spoke to Shivani Wagh, Joint Managing Director, Supriya Lifescience.
Supriya Lifescience has built a strong presence in niche APIs. How did the company perform during FY25-26, and how do you see your product portfolio evolving to meet changing global pharmaceutical demands?
Following a strong FY25 where we achieved Rs 706.3 crore in total revenue and a 57.8 per cent surge in net profit, FY26 has demonstrated tremendous momentum. While full-year audited numbers are being finalised, our Q3 FY26 results underscore our operational strength. In Q3, we reported 11.2 per cent year-on-year revenue growth to Rs 206.44 crore, with Profit After Tax rising to Rs 49.68 crore. This followed a stellar Q2 FY26 where revenue surged over 20 per cent to Rs 199.83 crore. Looking ahead, management remains highly confident in delivering approximately 20 per cent annualised revenue growth. Driven by the commissioning of our Ambernath formulation facility, new product launches, and expanding CMO contracts globally, we are firmly on track to hit our target of Rs 1,000 crore in revenue by FY27, scaling toward Rs 1,600 crore over the next three years.
Our portfolio is shifting towards advanced APIs and integrated Contract Development and Manufacturing Organisation (CDMO) services. Our product evolution is driven by global demand for supply chain resilience. In FY25, 85 per cent of our Rs 706.3 crore revenue came from exports, with highly regulated markets like Europe (37.1 per cent) and Latin America (21.8 per cent) leading. To secure this growth, we deepened backward integration to an industry-leading 81 per cent across 15 APIs. By producing our own Key Starting Materials (KSMs), we protect our portfolio from supply disruptions while maintaining strong EBITDA margins of over 35 per cent. Furthermore, our evolution is about moving from a pure API supplier to an end-to-end healthcare partner that provides tailored finished dosages.
Are there any new product segments or therapeutic areas that the company is particularly focused on strengthening in the near to medium term?
Yes, our portfolio diversification is highly targeted. While legacy segments are being consolidated, our medium-term growth engine is focused on growing challenging therapeutic areas. We are particularly expanding our footprint in the cardiovascular, liquid anaesthetics, contrast media, and antidiabetic markets. Furthermore, we are pleased about the impending Attention-Deficit/Hyperactivity Disorder (ADHD) releases, which represent a big opportunity in regulated geographies. Our strategic emphasis is focused on exclusive Contract Manufacturing Organisation (CMO) alliances. A notable example is our 10-year exclusive API supply contract for Vitamin B2 with European company DSM-Firmenich. Following subsequent approvals, notably those from Japan's PMDA, this deal is expected to generate peak annual revenues of Rs 60 crore by FY27. By establishing long-term CMO partnerships and introducing three to four specialised products a year, we make sure our pipeline is robust and precisely matched with the clinical requirements of our international clients.
Could you share some perspective on the role of R&D within the organisation? How is it evolving in terms of capabilities or focus areas?
Our margin resiliency is built upon the foundation of research and development. Currently, we have two R&D hubs in Lote and Ambernath, which house over 60 committed scientists. Historically, our R&D spending was roughly 1 per cent of revenue, but we are increasing it to 2 per cent as we take on more complex molecular difficulties. R&D plays the most important role in advancing our backward integration plan. Our scientific expertise recently allowed us to expand backward integration from 69 to 81 per cent, substantially preserving our bottom line from volatile external supply chains. In terms of capabilities, our R&D department is shifting from traditional synthesis to sophisticated continuous flow chemistry, green efforts, and complex formulation development for our CDMO Company. By focusing on highly regulated molecules with fewer active Drug Master Files (DMFs) globally, our scientists ensure we operate in high-barrier segments that deliver sustainable value.
Are there any upcoming projects, expansions, or capacity enhancements that you believe will play an important role in the company’s next phase of growth?
We are currently conducting a very strategic, debt-free capital investment cycle that is wholly supported by internal accruals. The recent commissioning of Module E at our Lote facility marked a significant milestone, adding 335 KL of multifunctional API capacity. This brings our total installed reactor capacity to 932 KLPD, allowing us to fulfil rising export demand. Our new Ambernath formulation facility will be the most significant catalyst in the near term. This cutting-edge plant, which cost Rs 155-160 crore to develop, became operational in Q4 FY26, marking our official entry into finished dosages and CDMO activities. Moving forward, we have obtained land in Patalganga for a Greenfield expansion. This project, which will cost around Rs 350 crore in its first phase, will allow for expansion whenever Lote and Ambernath attain their combined revenue potential, serving as the infrastructure foundation for our ambitious medium-term goals.
Given the changing global pharmaceutical landscape, what are the key opportunities and challenges you foresee for the Indian pharma sector going forward?
With a present valuation of about $58 billion, the Indian pharmaceutical industry is in a unique position to benefit from supply chain diversity. India, which supplies 20 per cent of the world's generics, has a unique chance to gain market share in essential APIs as other markets adopt "China plus One" tactics. According to industry estimates, the market would increase at a rate of 9–11 per cent by 2030, reaching $120–130 billion. However, doing this necessitates overcoming significant obstacles. Our reliance on imported KSMs, which exposes the sector to price volatility and geopolitical shocks, continues to be our greatest risk. Furthermore, overcoming the US Food and Drug Administration (US FDA) and European Medicines Agency’s (EMA) strict compliance criteria necessitates ongoing investment in high-quality infrastructure. Indian companies that prioritise significant backward integration, migrate quickly from high-volume generics to speciality pharmaceuticals, and maintain unwavering regulatory compliance will be successful in the coming decade.
Are there any major expectations from the government to further strengthen pharma innovation in the country?
The government's proactive approach, particularly through the Production Linked Incentive (PLI) plan, has proven beneficial. By late 2025, the project had successfully raised approximately Rs 4,760 crore in investments, establishing 55,100 metric tonnes of vital API capacity. However, in order for India to become a global innovation engine, policy frameworks need to adapt. Our fundamental assumption is that the Promotion of Research and Innovation Programme (PRIP) will be quickly operationalised in order to aggressively incentivise the creation of complex molecules and continuous flow chemistry. Secondly, the industry urgently requires streamlined, single-window regulatory and environmental clearances. Delayed approvals for capacity expansions directly hinder global competitiveness. Finally, long-term infrastructure investments, such as the development of bulk drug parks with centralised, subsidised utilities, will significantly lower overhead costs, allowing mid-sized businesses to compete fiercely on a global scale while adhering to rigorous environmental regulations.
Dr Manbeena Chawla
(manbeena.chawla@mmactiv.com)